
LANGLEY-BASED. SERVING CLIENTS ACROSS BRITISH COLUMBIA.
Your Home. Your Future. Your Mortgage Partner.
Clear, considered financing for your next home, refinance, or transition.
★★★★★
85+ 5-star Google reviews
2007
Guiding BC homebuyers
Unbiased advice. Straight answers.
Langley roots. British Columbia reach.
Based in Langley and serving clients throughout British Columbia, Jen provides mortgage guidance for buyers and homeowners in the Fraser Valley, Vancouver Island, the Okanagan, and beyond.
How can I help?
A CLEAR WAY FORWARD
Mortgage guidance through
separation and divorce.
When your home, finances, and future are changing, a clear mortgage plan can make the next step feel more manageable. Jen provides discreet guidance around your options, whether that means a spousal buyout, refinancing, or planning for your next home.
Mortgage guidance tailored to your situation. Independent legal advice may be appropriate.
A more considered mortgage process.
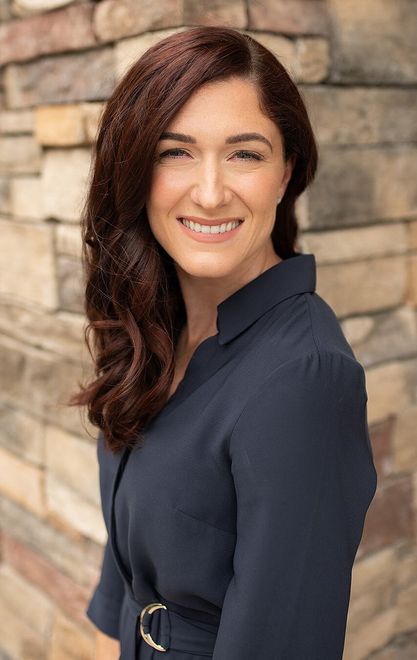
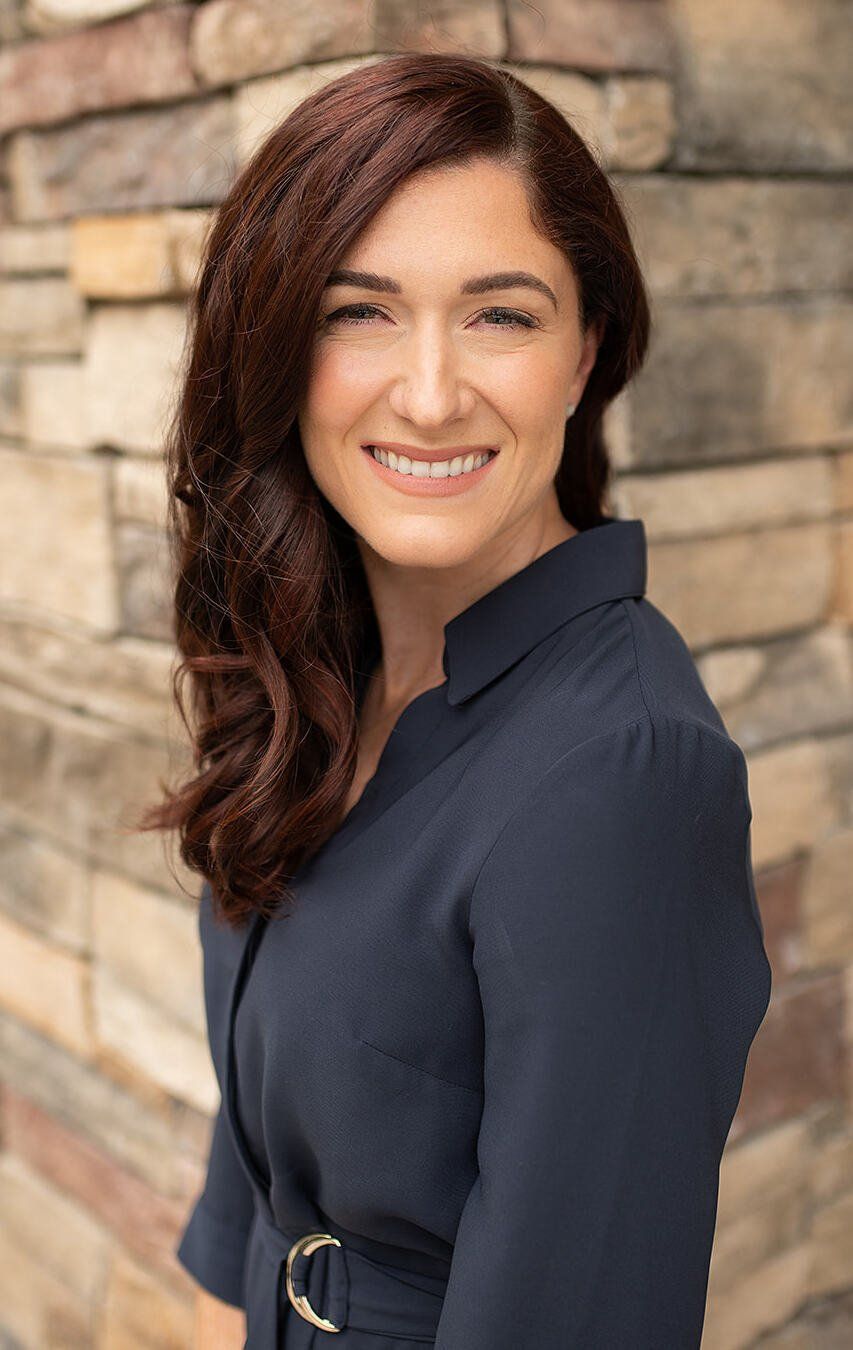
Jen Fuentes
Mortgage Broker & Franchise Owner
Hi, I’m Jen. I’ve been helping British Columbians finance their homes since 2008. I’m based in Langley and work with clients across the Fraser Valley, Greater Vancouver, Vancouver Island, the Okanagan and throughout the province.
Nearly Two Decades of Mortgage Experience
I started my career in 2008 with Dominion Lending Centres. In 2011 I opened my own DLC franchise, and for the next 15 years I ran that brokerage with my business partner. Along the way I built a team and trained new sub-brokers.
Teaching other brokers shaped how I work with my own clients. I learned that good mortgage advice means explaining the why, not just quoting a rate. I want you to understand your options well enough to make a confident decision.
A New Chapter
In October 2026 I joined BrokerSquared Paragon Mortgage Group, operating as Jen Fuentes Personal Mortgage Corporation. This move lets me put my full focus back where it matters most, which is working directly with my clients. You still get the lender access, experience and attention to detail you’d expect, with a more personal experience from first conversation to closing.
Where I Can Help Most
- RCMP members and families: As the wife of an RCMP member, I know firsthand what postings, transfers and relocations involve. I’ve helped many members and their families with lending and moves across Canada.
- Separation and divorce: Changes to your home and finances during a separation call for care and discretion. I’ll help you understand your options, whether that’s a spousal buyout, a refinance or planning your next home.
- Buying, renewing and refinancing: From first-time buyers to experienced homeowners, I’ll find financing that supports your bigger picture, not just the lowest advertised rate.
Life Outside the Office
I’m a mom of three busy kids who love playing sports, so our family spends a lot of time at rinks, fields and ball diamonds. We live an active lifestyle and love being part of the Langley community. I also volunteer with Langley Minor Hockey and North Langley Baseball, because supporting youth sports is something our whole family believes in.
Let’s Talk
Whether you’re buying your first home, coming up for renewal or navigating a big life change, a clear conversation is the best place to start.
Advice that stays with you.
Since 2007, Jen has helped BC homeowners make well-informed mortgage decisions with honest answers, practical education, and consistent communication. Her approach is personal, responsive, and focused on finding financing that supports the bigger picture, not simply the lowest advertised rate.
Mortgage clarity, when you need it.
Should I refinance before renewal?
Read article →
What to know before a BC mortgage pre-approval
Read article →
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
Can’t Find the Right Home After You’re Pre-Approved? There’s Another Option The best place to start any home purchase is with a mortgage pre-approval. It gives you clarity around your budget and lets you shop with confidence. But what happens when you’ve been pre-approved, you know where you want to live—and nothing suitable fits your price range? This is a common challenge, especially for first-time homebuyers. Before buyer fatigue sets in, it may be worth considering a different approach: buying a home that needs work and financing the renovations as part of your mortgage . What Is a Purchase Plus Improvements Mortgage? A purchase plus improvements program allows you to buy a property and include the cost of approved renovations directly in your mortgage. This can be a great solution if: You can’t find a move-in-ready home within budget You’re open to renovations You want to customize the home from the start It opens up more options and can help you get into a location or property that would otherwise be out of reach. How the Process Works While the idea is straightforward, the process itself is structured and requires planning. Here’s a high-level overview: Renovation quotes are required upfront You’ll need detailed quotes for the work you want completed before final mortgage approval. Renovations must add value The lender must be satisfied that the improvements will increase the property’s value accordingly. Funds are reimbursed, not advanced You pay for the renovations initially. Once the work is completed and verified by an appraiser, the lender reimburses you and adds the cost to your mortgage. With the right guidance, this process is very manageable—but it’s important to understand the steps before committing. Is This Program Right for You? Purchase plus improvements isn’t for everyone. Buying a home is already a big undertaking, and adding renovations can increase stress—especially if timelines, budgets, or contractors become challenging. That said, if you’re financially prepared and like the idea of shaping the home to fit your needs, this program can be an excellent way to get more value and flexibility from your purchase. Final Thoughts If you’re struggling to find the right home after being pre-approved, you may not need to lower your expectations—you may just need a different strategy. If you’d like to explore whether a purchase plus improvements mortgage makes sense for you, feel free to connect. I’d be happy to walk you through the process and outline exactly what this option would look like in your situation.
Missed a Credit Card or Line of Credit Payment? Here’s What to Do If you’ve missed a payment on a credit card or line of credit and you’re worried about how it might affect your credit—or your future mortgage—this is for you. First things first: 👉 If you currently have an overdue balance, log in and make the minimum payment now. Seriously. Do that first. Everything else can wait. If You’re Only a Few Days Late Here’s the good news: Credit bureaus don’t record late payments until they reach 30 days past due. So if you missed a due date by a few days and paid it as soon as you noticed, it typically won’t show up on your credit report as a late payment—as long as you’re under the 30-day mark. That said, it never hurts to double-check. You can call your credit card company, explain what happened, and confirm the account is back in good standing. If you normally pay on time, they may even reverse the interest charged. It doesn’t hurt to ask. If You’re 30, 60, or 90 Days Behind If payments have gone past 30 days, your credit has likely been impacted—but the situation is still fixable. The most important step is to: Bring all accounts current as soon as possible Make at least the minimum payment on every account The faster you catch up, the more you limit the damage. Ignoring missed payments only makes things worse. If Cash Flow Is Tight If you’re struggling to make payments, communication matters. Contact your lender and keep them informed—even if you can’t pay right away. Lenders are far more willing to work with you when you’re transparent. What hurts your credit most is silence . If lenders don’t hear from you after repeated missed payments, they may write the balance off as bad debt and send it to collections. Collections can significantly impact your credit and stay on your report for years. How This Affects Mortgage Qualification Repeated missed payments can make qualifying for a mortgage more difficult—but timing matters. Once you’re back to making regular, on-time payments: Your credit can improve over time The impact of past mistakes becomes less significant If you’re planning to buy a home in the next couple of years, addressing credit issues early gives you far more options later. Final Thoughts Missing a payment doesn’t mean you’re “bad with money,” and it doesn’t mean homeownership is off the table. What matters most is how quickly you respond and how consistent you are going forward . If you’d like help reviewing your credit report or understanding where you stand from a mortgage perspective, feel free to connect. I’d be happy to walk through it with you and help you create a clear path forward.
Mortgage questions, answered clearly.
Whether you are buying, renewing, refinancing, or planning a change, a clear conversation is a good place to start.
Where do you work with clients?
Jen is based in Langley and works with mortgage clients throughout British Columbia, including the Fraser Valley, Greater Vancouver, Vancouver Island, and the Okanagan. Conversations can happen in the way that works best for you, including by phone, video, or in person when appropriate.
How do I know which mortgage is right for me?
The right mortgage is about more than a rate. Your payment, term, flexibility, prepayment options, future plans, and comfort level all matter. Jen starts by understanding your situation and then helps you review the options that may fit your goals.
Do I need a mortgage pre-approval before I start looking?
A pre-approval can be a helpful first step because it gives you a clearer view of your borrowing position and the documents you may need. It is not final approval, but it can help you begin your home search with more confidence.
Can you help if I am self-employed, renewing, refinancing, or separating?
Yes. Every mortgage situation has its own questions. Jen provides guidance for home purchases, refinancing, renewals, self-employed clients, next-home planning, and mortgage questions that can arise during separation or divorce.
What does it cost to work with a mortgage professional?
For many standard residential mortgage transactions, the lender pays the mortgage professional’s compensation. Some situations can involve fees or additional costs. Jen will explain the details that apply to your file before you move forward.
How do I get started?
Start with a conversation. Share where you are now, what you are hoping to accomplish, and any timing that matters. Jen can help you identify the next questions, documents, and mortgage options worth exploring.
Still have a question?
Let’s start with a clear conversation.
Tell me where you are now, and we’ll map out the mortgage options that make sense for you.
Langley-based | Serving clients across British Columbia